Services
Wind, hail and fallen limbs. We handle the roof and the paperwork.
A storm-damage inspection that is free, photographed from every angle, and written up the way insurance adjusters expect to read it.
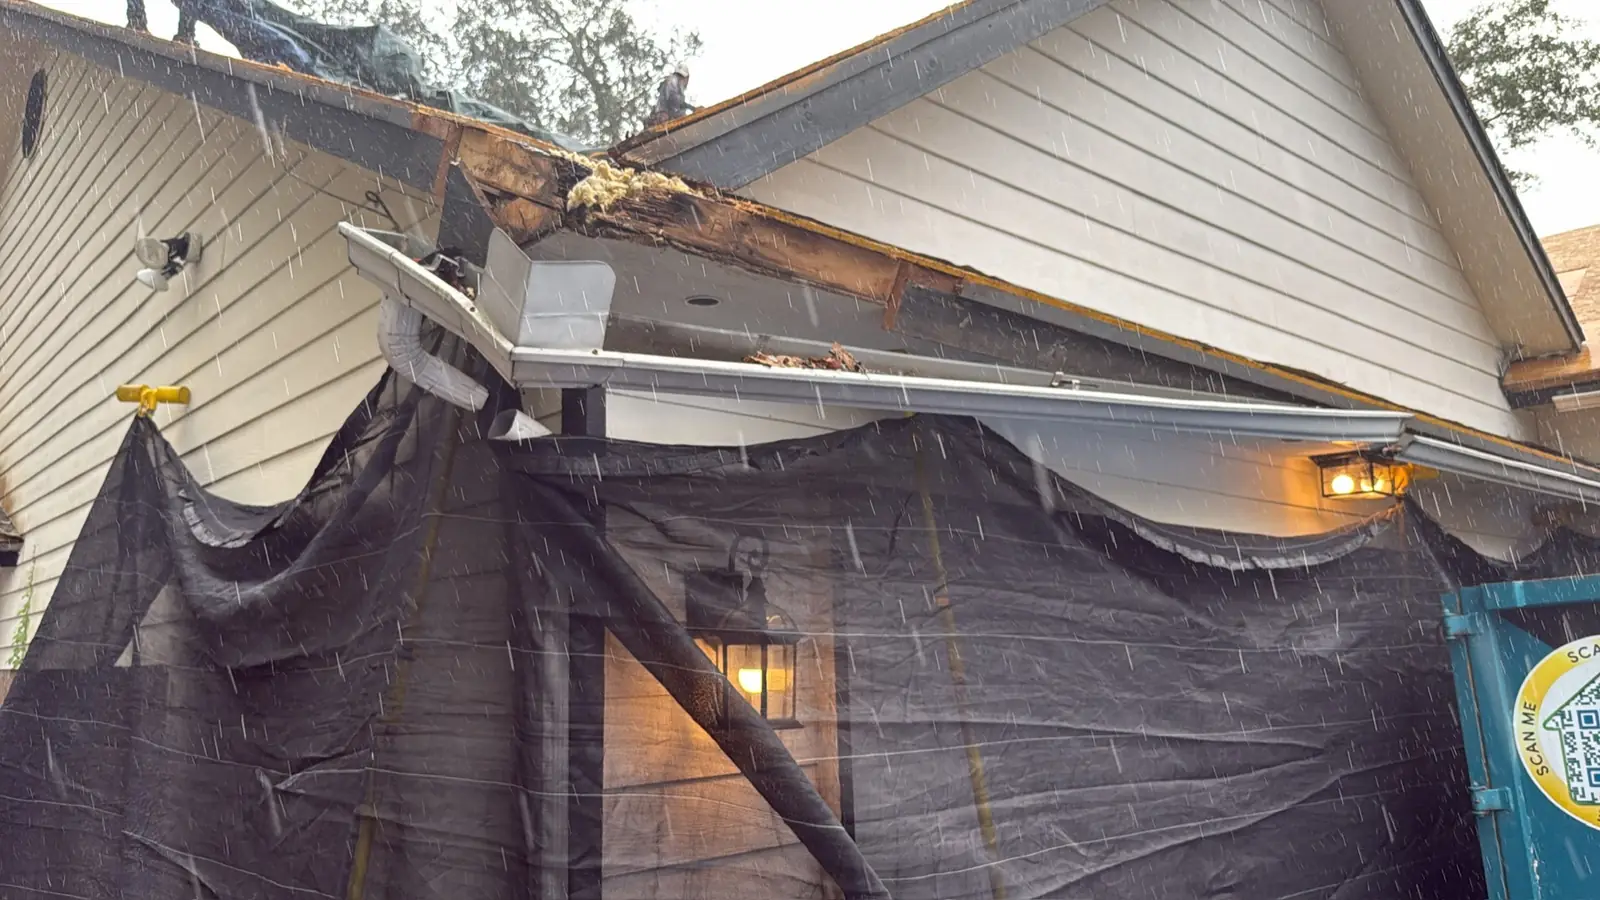
Storm damage is often invisible from the ground: creased shingles that will tear off in the next blow, granule loss that exposes the asphalt, hail bruises that turn into leaks a year later. We find it, photograph it, and put it in a report that speaks the adjuster’s language.
If water is getting in, we tarp first and talk later. Then we document the roof, help you open the claim if you decide to file, and meet the adjuster on the roof so nothing gets missed. When the scope comes back short, we submit the supplement with the photos to prove it.
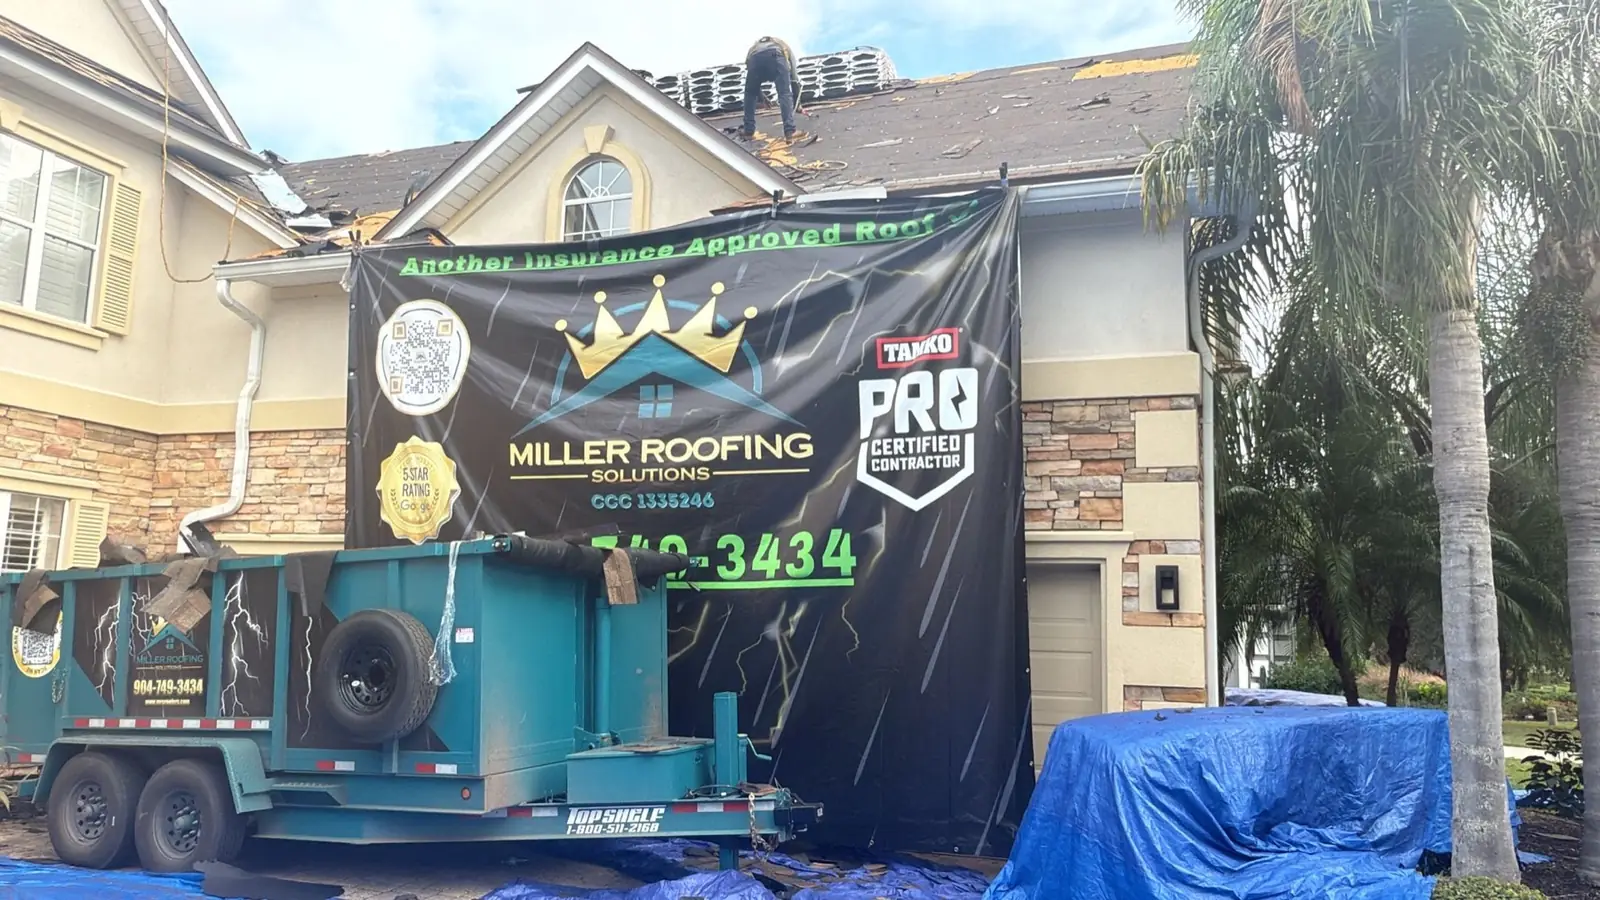
Our banners say “Another insurance-approved roof” for a reason: we have walked hundreds of homeowners through this exact process.
More help
Storm resources
Storm emergency: what to do now
Five steps for the first hour after damage, including what not to sign.
Read the guideHow insurance claims work
The process, the law, and the decisions that stay yours.
Claims explainedFORTIFIED and wind mitigation
Build back stronger and earn insurance discounts while you’re at it.
See the optionsHow it works
Secure, document, build.
- 01Secure
Tarp the damage and stop the water. Same day whenever possible.
- 02Document
Full roof inspection with photos, measurements and a written summary.
- 03File
You open the claim with your carrier. We give you everything they will ask for.
- 04Adjust
We meet the adjuster, walk the damage, and handle supplements.
- 05Build
Permitted, inspected, photographed, and usually done in a day.
Questions
Storm Damage & Insurance: your questions.
Should I file a claim?
Only if the damage is real and the repair cost is clearly above your deductible. We inspect first, show you what we found, and give you an honest read. Plenty of inspections end with “this is a repair, not a claim.”
Will you cover my deductible?
No. Florida law prohibits contractors from waiving or paying deductibles, and any roofer offering to is committing insurance fraud with your name on the claim. We will show you financing options for it instead.
The storm was months ago. Is it too late?
Maybe not. Policies set their own notice and filing windows, and some damage only shows up later. We inspect, document the date-of-loss evidence we can find, and tell you straight whether a claim is realistic.
Next step
Let’s put eyes on your roof this week.
Free inspection. Written findings. Photos you keep. Zero pressure.